New Institutional Report Released
Access our strategic market perspective on necessity-based real estate and private credit fundamentals.
Read Full Report
Over fifteen years, OTIMA-sponsored Investment Entities acquired income-producing U.S. real estate one deal at a time — $205M+ in assets under management (AUM), 68 completed transactions, an 18.5% average deal IRR. Our funds take that discipline and give investors access to a diversified portfolio of it in a single, professionally governed vehicle.
WHY WE BUILD FUNDS
For most of our history, investors came into OTIMA deals one asset at a time. It worked - the track record is the evidence - but it asked a lot of the investor. Every deal was a fresh decision, a fresh subscription, and a fresh concentration risk in a single property with a single tenant base.
A fund solves that. One commitment, one set of documents, one relationship - and exposure to a portfolio of assets across sectors and markets rather than a bet on one building. Capital gets deployed as opportunities appear instead of sitting idle waiting for the next offering. Distributions come from a portfolio rather than a property.
We're building a family of funds, not a single vehicle. Each has a defined mandate, its own governing documents, its own investor base, and its own capital. What they share is our underwriting and our money alongside yours. As the platform grows, strategies extend - different sectors, different risk profiles, different hold horizons - but the discipline underneath doesn't change.
Single Property / Single tenant base
One set of Documents
WHAT EVERY OTIMA FUND SHARES
01
Principal co-investment in every fund and every deal, on the same terms as our investors. Investor distributions are paid first, and our economics are performance-linked. We do well when the portfolio does.
02
Every asset produces cash on day one. Distributions are paid quarterly from operating income, not from an exit we're hoping for. Appreciation is upside - it's never the plan.
03
We underwrite the bad case before the base case. Investment-grade and operationally-anchored tenants, long lease terms locked at entry, conservative leverage, supply-constrained submarkets, and hard concentration limits on any single tenant or asset.
04
Third-party fund administration, independent legal and tax counsel, external audit, an investment committee, and an LP advisory committee with real authority over conflicts and valuations. Quarterly investor reporting as standard.
05
You get the people making the decisions, not an investor relations queue. Quarterly reporting, and a phone number that works in between.
OUR FUNDS
FUND I · OPEN TO ACCREDITED INVESTORS
ENDURE THE CYCLE. CAPTURE THE RETURN.
An income-focused U.S. real estate fund built on the thesis that necessity retail, medical outpatient and select multifamily are mispriced relative to how reliably they pay. Closed-end, five-to-seven year term, quarterly distributions, hybrid master-LP structure with a U.S. blocker enabling both U.S. and non-U.S. investors.
ALLOCATION TARGETS
IN DEVELOPMENT
The next vehicle on the platform. Mandate and terms are being finalized. If you'd like to be told when it opens, join the list.
You're on the list. We'll let you know when Fund II opens.
FUND I
ENDURE THE CYCLE. CAPTURE THE RETURN.
A - THE INVESTMENT THESIS
Endura exists because of a specific disagreement with the market. Necessity retail and medical outpatient sit at the top of the commercial real estate yield curve while carrying the lowest tenant default risk in the sector — and the market has been slow to correct that. Endura is built to own that spread, across a diversified portfolio, through a full cycle.
The timing is the other half of it. U.S. commercial real estate corrected 15%+ from its 2023 peak and has posted four consecutive quarters of positive returns. More than $1 trillion of CRE debt matures in 2026–27. New supply across all three target sectors has stalled. Entry pricing today is the best it has been in a decade, and it is not a permanent condition.
B - SECTOR ALLOCATION
Grocery-anchored and daily-needs centers, and single-tenant net lease in pharmacy and dollar formats. Investment-grade anchors on 5–15 year absolute NNN leases. Highest yield in CRE, lowest default risk, insulated from e-commerce.
RETAIL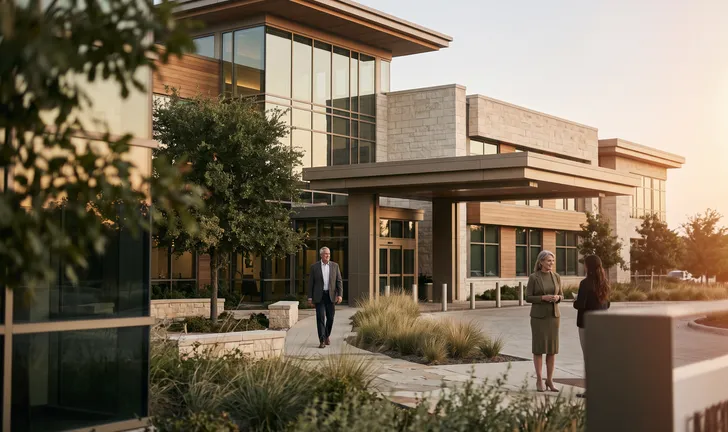
Medical outpatient and clinic-based properties in high-density catchment areas. 10–15 year leases with health systems and specialist groups, high renewal probability, structural demographic demand.
HEALTHCARE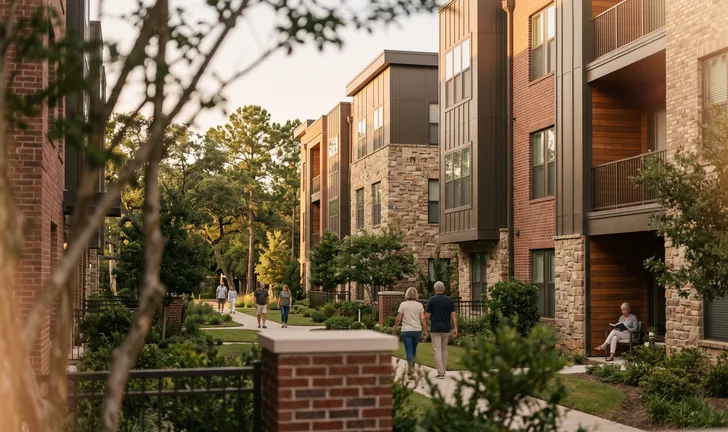
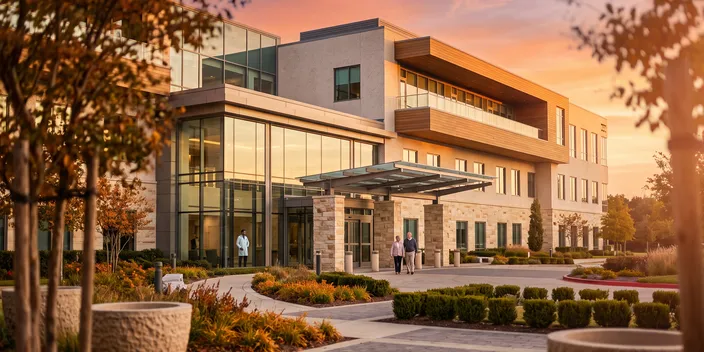
Well-located assets in supply-constrained Sun Belt and gateway markets. Annual rent resets, value-add repositioning potential, allocated dynamically on relative value at acquisition.
MULTIFAMILYC - RISK MITIGATION
ENDURA’S APPROACH
Endura focuses on investment-grade anchors on absolute NNN leases. Tenants are responsible for operating costs, and rent remains contractually due regardless of business performance, creating a more durable income structure.
ENDURA’S APPROACH
Long-term weighted average lease terms (WALT) of 10–15 years across credit anchors insulate against frequent rollover, while structured extension options provide multi-cycle predictability.
ENDURA’S APPROACH
We acquire at significant basis discounts to historical replacement costs, underwriting conservative terminal cap rates and relying on high current cash distributions rather than terminal multiple expansion.
ENDURA’S APPROACH
Targeting non-discretionary necessity retail (grocery, pharmacy, discount) and essential healthcare clinics ensures revenue streams remain robust even during broad consumer spending contractions.
ENDURA’S APPROACH
We target infill, highly constrained micro-locations in mature submarkets where physical land scarcity, high construction costs, and municipal barriers severely restrict competitive new supply.
ENDURA’S APPROACH
Portfolio diversification across three distinct, counter-cyclical asset classes (necessity retail, medical outpatient, multifamily) and strict single-tenant / single-asset allocation caps across regional growth hubs.
WHO OUR FUNDS ARE FOR
01
Dedicated structures seeking direct co-investment alongside an aligned operating partner with genuine local execution.
02
Advisor networks and platform distributors providing scalable client access to private real estate strategies.
03
High and ultra-high-net-worth individuals looking for institutional-grade real estate exposure without buying and managing buildings themselves.
Our funds are offered only to accredited investors, by private placement, through the fund's offering documents. Nothing on this page is an offer to sell or a solicitation to buy any security.
TRACK RECORD
*Track Record & Prior Investment Experience: Information regarding prior investments, acquisitions, dispositions, distributions, operating results, or performance-related metrics is provided solely to describe the historical experience of OTIMA, its principals, and/or affiliates in specific prior transactions. A principal's involvement in a prior transaction may have been in a capacity different from their role in future OTIMA-sponsored investments. Past performance is not indicative of and does not guarantee future results. All investments involve risk, including the possible loss of principal. Prospective investors should not rely on prior results as a prediction or guarantee of future performance.Read full disclosure →
Please confirm your accredited investor status to view the full track record.